Can you send a COI before the siding and gutter project starts?
Insurance that helps you say yes to the next exterior job.
Prefer to talk? Call +1 802-GOT-RIZA
Meet homeowner and project requirements before work starts.
Add crews, trucks, lifts, and forming equipment as the business grows.
Show gutter, siding, soffit, fascia, and height exposure in one clear review.
Property owner requests insurance evidence for multi-building exterior replacement. Riza reviews the operation and requirements, then confirms the gutter and siding business can move forward.
The exterior protects the building. Insurance should help protect the business installing it.
Clear the requirement. Staff the project. Keep crews, trucks, lifts, brakes, materials, and completed work moving.
01Contract requirementLiability limits and endorsementsMapped
02Operational changeSecond crew, truck, and liftAdded
03Job accessCertificate packageReady
Get cleared before ladders and lifts arrive.
Organize limits, certificates, height, access, and customer requirements before setup.
Show every exterior system.
Gutters, siding, soffit, fascia, windows, roofing, sheet metal, and water-management work can change carrier fit.
Protect the building around the install.
Build around weather exposure, customer property, crews, vehicles, equipment, materials, and completed work.
Coverage built around your exterior work.
Coverage fit
Built around height, water management, and mobile forming.
Common details that shape the quote:
- Seamless forming, downspouts, guards, and repair
- Maximum height, ladders, lifts, and roof-edge access
- Trucks, trailers, brakes, coils, and completed work
 Gutter installation
Cover what keeps your exterior business moving.
Height, weather, customer property, crews, trucks, lifts, forming equipment, and materials create different insurance needs.
Protect the building after the final piece goes on.
Help protect the business from covered injury, property damage, and completed-work claims arising from eligible gutter and siding operations.
Explore general liability →
Protect the people working above ground.
Support state requirements and benefits for covered employee injuries as field and service payroll grows.
Explore workers’ comp →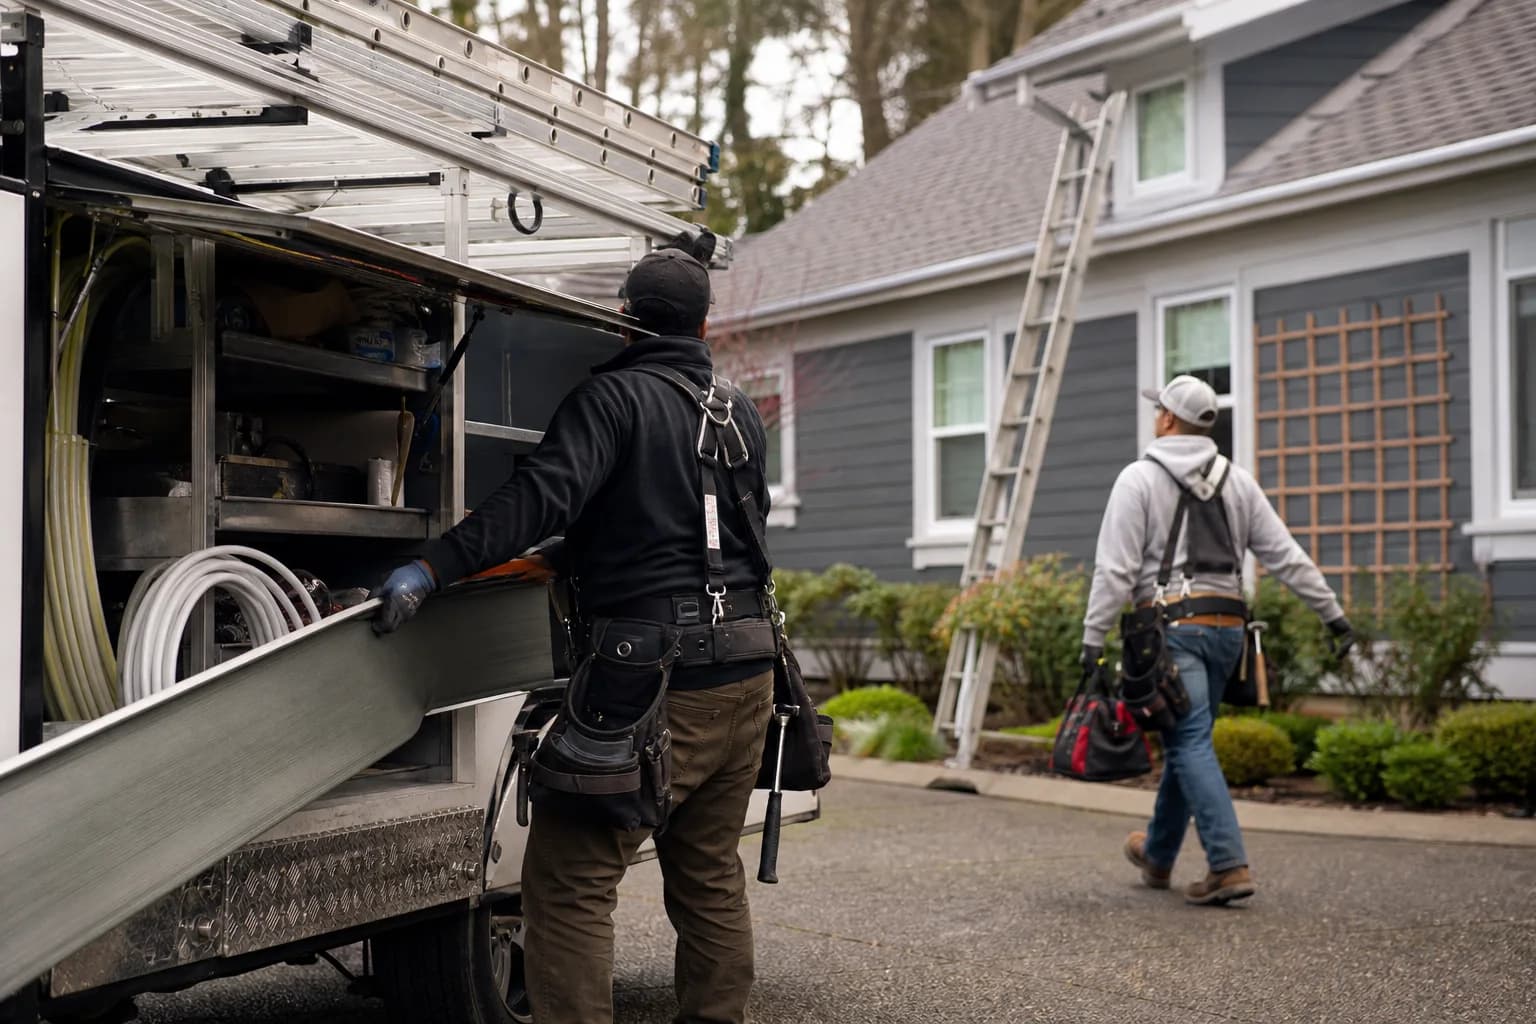
Keep crews, coils, panels, and equipment moving.
Help protect eligible work vehicles and drivers carrying people, parts, tools, and equipment between customer locations.
Explore commercial auto →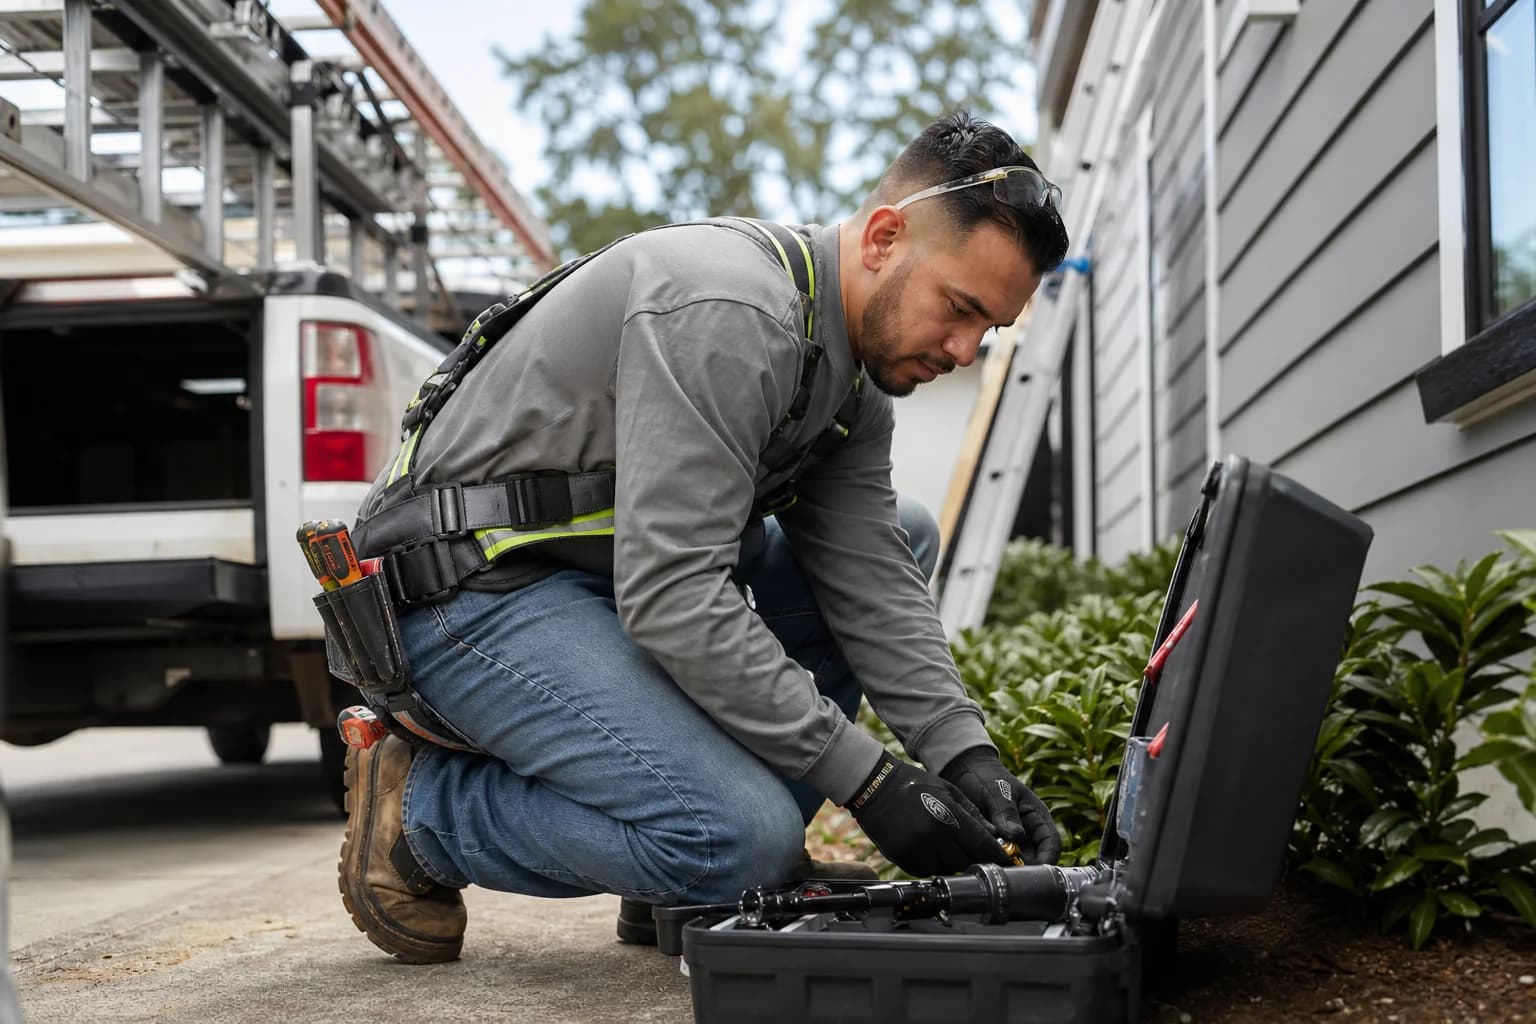
Protect brakes, lifts, and installation tools.
Help protect eligible tools, diagnostic instruments, and mobile equipment between the shop, vehicles, and jobsites.
Explore tools and equipment →Need more than the core policies? Add property, umbrella and excess, installation, builders risk, cyber, and other available coverage to the same review.
Explore all coverageAlready insured?
A better renewal starts with the policy you already have.
Send it once. We’ll compare it with today’s exterior systems, heights, crews, vehicles, lifts, equipment, projects, and available options.
Send
Compare
Choose
Illustrative example. Availability, eligibility, pricing, coverage, and terms depend on carrier underwriting and the policy.
Your questions, answered.
What you may want to know before you buy or switch.
What insurance does a gutter or siding contractor usually need?
Gutter and siding contractors often consider general liability, workers’ compensation, commercial auto, and tools and equipment coverage. Property, business income, umbrella or excess, pollution, professional, cyber, installation, or other coverage may also matter depending on the operation and carrier eligibility.
Why do height, water management, and material type matter?
Working height and access affect employee and liability risk, while flashing, wrap, gutters, and siding affect water intrusion and completed-work exposure. Material types, hot work, removal, and roof or window operations should be identified accurately.
Can Riza review my current a gutter or siding contractor insurance before renewal?
Yes. Send the current policies, loss runs, vehicle and driver information, payroll, revenue, gutter and siding mix, materials, heights, access methods, crews, vehicles, forming equipment, and projects, and representative contract requirements. Riza can organize the submission and compare available options.
What affects the price of a gutter or siding contractor insurance?
Carrier pricing can reflect maximum height, ladders and lifts, siding materials, roof-edge work, removal, new construction, revenue, payroll, vehicles, equipment, and loss history, locations, states, limits, deductibles, and loss history. Carrier appetite and the complete policy structure also affect the available options.
Ready for
the next job?
Tell us about your gutter or siding business or send your current policy. We’ll help organize the next step.
Prefer to talk? Call +1 802-GOT-RIZAMon-Sun, 8am-8pm ET