
Workers’ comp insurance
hurt on the job? they’re covered.
Medical bills and lost wages are covered, and you stay on the right side of state law. We find the right price for your payroll.
get startedMARKETS WE PLACE THROUGH



your crew, covered.
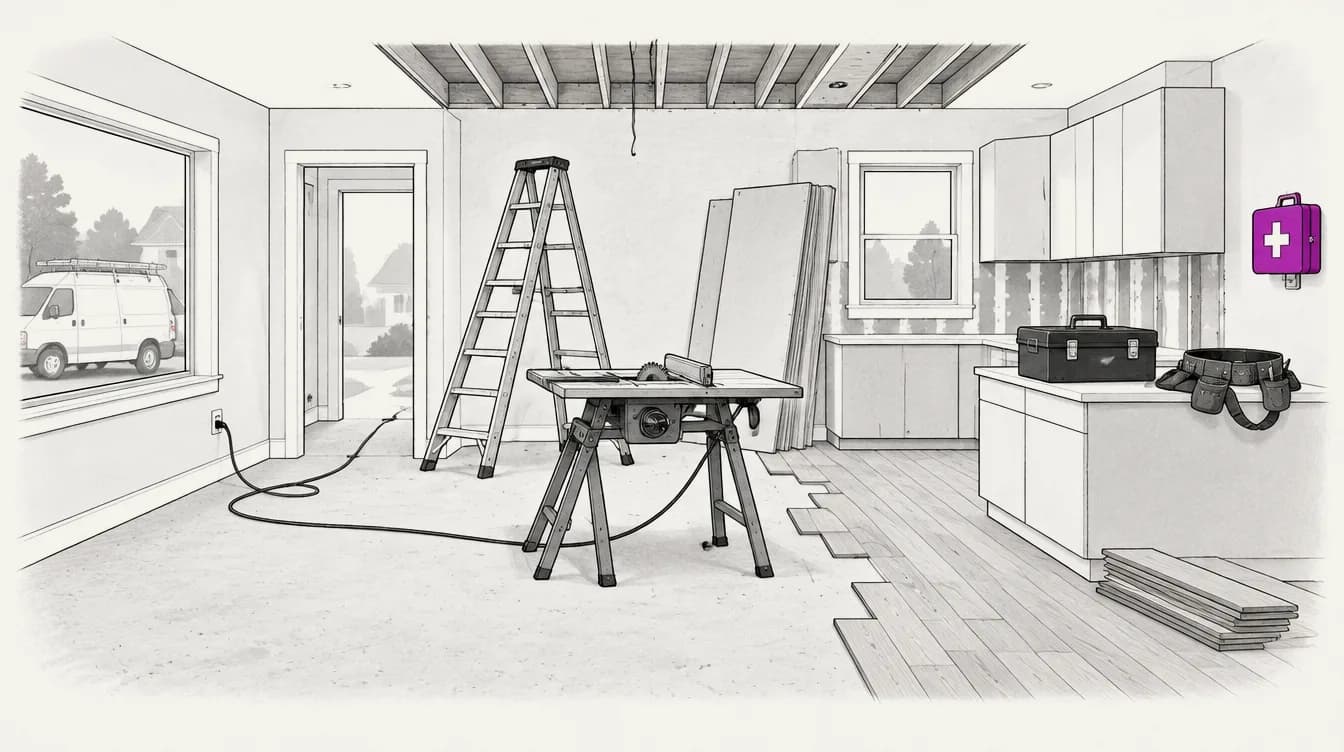
Falls, strains, cuts, even the drive between jobs. Tap around the site to see what’s covered, and what isn’t.
covered
Someone falls off the ladder
Medical bills and lost wages while they heal.
covered
A back injury lifting drywall
Strains count, not just accidents.
covered
A cut on the table saw
The ER visit and the follow-up care.
covered
Hurt driving between jobs
Driving for work usually counts.
not covered
You, if you opted out
Many states let owners opt out. We’ll check yours.
covered
Someone falls off the ladder
Medical bills and lost wages while they heal.
Examples. Your policy sets the details.
hiring? know the rules first.
Most states require it from your first employee. Pick yours and we’ll tell you what applies.
Generally required once an Alabama employer has 5 or more employees.
Corporate officers and LLC members generally count. Some residential construction work can trigger coverage sooner. We confirm what applies when you start.
Generally required in Alaska with 1 or more employees.
Part-time and temporary employees generally count. Owner and industry exemptions can apply. We confirm what applies when you start.
Generally required in Arizona with 1 or more employees.
Full-time, part-time, minor, and family employees generally count. Domestic workers and true independent contractors may be exempt. We confirm what applies when you start.
Generally required in Arkansas with 3 or more employees.
Some employers with fewer than 3 employees can still be covered by the law, so the business and work must be checked. We confirm what applies when you start.
Generally required in California with 1 or more employees.
California roofers generally must carry coverage even when they have no employees. Owner exclusions are limited and fact-specific. We confirm what applies when you start.
Generally required in Colorado with 1 or more employees.
Part-time employees generally count. Limited owner, domestic-work, and casual-work exceptions can apply. We confirm what applies when you start.
Generally required in Connecticut with 1 or more employees.
Full-time and part-time employees generally count. Uninsured subcontractor exposure and owner elections should be reviewed. We confirm what applies when you start.
Generally required in Delaware with 1 or more employees.
Farm labor, true independent contractors, and certain owner or family-member elections can change the result. We confirm what applies when you start.
Generally required in Florida with 4 or more non-construction employees, or 1 or more construction employees.
Construction has the stricter trigger. Agriculture uses separate regular- and seasonal-worker thresholds. We confirm what applies when you start.
Generally required in Georgia with 3 or more employees.
Full-time, part-time, temporary, and seasonal employees generally count. Uninsured subcontractors can create exposure for contractors. We confirm what applies when you start.
Generally required in Hawaii with 1 or more employees.
Full-time, part-time, permanent, and temporary employees generally count. Owner and domestic-worker exemptions can apply. We confirm what applies when you start.
Generally required in Idaho with 1 or more employees.
Full-time, part-time, seasonal, and occasional employees generally count. Household and certain casual workers may be exempt. We confirm what applies when you start.
Generally required in Illinois with 1 or more employees.
Construction, trucking, and other hazardous work receive especially strict treatment. Owner treatment depends on entity type and work performed. We confirm what applies when you start.
Generally required in Indiana with 1 or more employees.
Building-trade independent contractors need the proper exemption certification. Owner and officer elections can apply. We confirm what applies when you start.
Generally required in Iowa with 1 or more employees.
Owner treatment varies by entity type. Qualifying independent contractors and limited agricultural or domestic work may be exempt. We confirm what applies when you start.
Generally required in Kansas when annual gross payroll exceeds $20,000.
The trigger is payroll, not employee count. Agricultural employers and some owner compensation are treated differently; subcontractors require special attention. We confirm what applies when you start.
Generally required in Kentucky with 1 or more employees.
Part-time employees generally count. Owners, farm labor, domestic workers, and federally covered work can be treated differently. We confirm what applies when you start.
Generally required in Louisiana with 1 or more employees.
Part-time employees generally count. Owner elections and the status of subcontractors should be reviewed. We confirm what applies when you start.
Generally required in Maine with 1 or more employees.
Owners are often excluded unless they elect coverage. Domestic, agricultural, aquacultural, and seasonal-work exceptions can apply. We confirm what applies when you start.
Generally required in Maryland with 1 or more employees.
Owner elections and limited agricultural exceptions can apply. The facts of the working relationship control. We confirm what applies when you start.
Generally required in Massachusetts with 1 or more employees.
Coverage usually applies regardless of hours worked. Owners and certain domestic or commission-based workers may be treated differently. We confirm what applies when you start.
Michigan generally requires coverage for employers with 3 or more employees, or 1 employee working at least 35 hours a week for 13 weeks or longer.
Agriculture and closely held businesses have separate rules. Owner, officer, and family-member treatment can change the result. We confirm what applies when you start.
Generally required in Minnesota with 1 or more employees.
Minors and non-citizens generally count. Closely held businesses, family operations, and some agricultural work can qualify for exclusions. We confirm what applies when you start.
Generally required in Mississippi with 5 or more regular employees.
Employers below the threshold may buy coverage voluntarily. Farm labor, domestic work, owners, and some officers may be treated differently. We confirm what applies when you start.
Generally required in Missouri with 5 or more employees, or 1 or more employees for a construction business.
Construction has the stricter trigger. Farm labor, domestic work, occasional labor, and owner elections can change the result. We confirm what applies when you start.
Generally required in Montana with 1 or more employees.
Construction employees working in Montana generally require coverage. Certified independent-contractor and owner rules should be checked. We confirm what applies when you start.
Generally required in Nebraska with 1 or more employees.
Part-time employees and minors generally count. Domestic, agricultural, federal, and true independent-contractor exceptions can apply. We confirm what applies when you start.
Generally required in Nevada with 1 or more employees.
Construction receives strict treatment. Owner elections, temporary out-of-state work, agricultural work, and limited casual labor can be treated differently. We confirm what applies when you start.
Generally required in New Hampshire with 1 or more employees.
Family members generally count. Closely held entities with no other employees and certain owners may qualify for exclusions. We confirm what applies when you start.
Generally required in New Jersey with 1 or more employees.
Corporate officers generally must be covered. Sole proprietors, partners, and LLC members without employees are treated differently. We confirm what applies when you start.
Generally required in New Mexico with 3 or more employees; construction employers generally need coverage with 1 or more.
Construction has the stricter trigger. Owner elections and agricultural, domestic, or real-estate exceptions can apply. We confirm what applies when you start.
Virtually all New York employers must provide coverage when they have 1 or more employees.
Part-time, temporary, seasonal, casual, leased, borrowed, and many family workers generally count. Owner-only entities can qualify for limited exceptions. We confirm what applies when you start.
Generally required in North Carolina with 3 or more employees.
Corporate officers generally count toward the threshold even if excluded from benefits. Trucking, radiation work, and agricultural employers can follow different rules. We confirm what applies when you start.
Generally required in North Dakota before employing 1 or more employees.
Full-time, part-time, and seasonal employees generally count. Owners, verified independent contractors, farm labor, and domestic workers can be treated differently. We confirm what applies when you start.
Generally required in Ohio with 1 or more employees.
Sole proprietors, partners, certain LLC members, and owner-only entities may elect or decline coverage depending on structure. We confirm what applies when you start.
Generally required in Oklahoma with 1 or more employees.
Owner elections and the family-of-five-or-fewer exemption can apply. Agricultural, domestic, and certain commission-based workers may be exempt. We confirm what applies when you start.
Generally required in Oregon with 1 or more employees.
Oregon has numerous statutory exemptions, so owner, domestic, agricultural, casual, and independent-contractor status should be checked. We confirm what applies when you start.
Generally required in Pennsylvania with 1 or more employees.
Part-time and family employees generally count. Owners, domestic or casual workers, some agricultural work, and commission-only roles may be exempt. We confirm what applies when you start.
Generally required in Rhode Island with 4 or more employees.
Owners, partners, independent contractors, and some agricultural, domestic, or commission-based workers may be treated differently. We confirm what applies when you start.
Generally required in South Carolina with 4 or more regular employees.
Uninsured subcontractors can create exposure for a general contractor. Agriculture, railroads, low-payroll employers, and owners can follow different rules. We confirm what applies when you start.
South Dakota does not generally require private employers to carry workers’ compensation coverage.
The state strongly recommends coverage because an uninsured employer can be sued by an injured worker. Contracts can still require a policy. We confirm what applies when you start.
Generally required in Tennessee with 5 or more employees; construction and coal-mining employers generally need coverage with 1 or more.
Construction has the stricter trigger and can include subcontractor exposure. Family members, part-time employees, and officers generally count toward the threshold. We confirm what applies when you start.
Most Texas private employers can choose whether to carry workers’ compensation coverage.
Public employers and construction contractors working for government entities generally must provide coverage. Customer contracts can also require it. We confirm what applies when you start.
Generally required in Utah with 1 or more employees.
General contractors must verify subcontractor coverage. Owner, agricultural, casual, domestic, and certain commission-based exceptions can apply. We confirm what applies when you start.
Generally required in Vermont with 1 or more employees.
Businesses using independent contractors should document responsibility for coverage. Owner, casual-work, and limited agricultural exceptions can apply. We confirm what applies when you start.
Generally required in Virginia when an employer regularly has more than 2 employees.
That ordinarily means 3 or more. Part-time, seasonal, temporary, trainee, minor, immigrant, and working family-member employees generally count. We confirm what applies when you start.
Generally required in Washington with 1 or more employees.
Owner elections and limited domestic, residential-maintenance, family-farm, entertainment, and leased-space exceptions can apply. We confirm what applies when you start.
Generally required in West Virginia with 1 or more employees.
Owner exclusions and limited agricultural, casual, domestic, church, professional-sports, and federally covered exceptions can apply. We confirm what applies when you start.
Wisconsin generally requires coverage at 3 or more employees, or after paying $500 or more in combined gross wages in a calendar quarter.
The wage trigger can make coverage apply with fewer than 3 employees. Agriculture, owners, LLC members, and closely held corporations follow separate rules. We confirm what applies when you start.
Generally required in Wyoming for employees working in covered industries.
Wyoming uses industry classifications and statutory exclusions, so the work performed matters in addition to employee status. We confirm what applies when you start.
Generally required in Washington, DC with 1 or more employees.
A sole proprietor without employees is generally not required to cover themselves. Special domestic-worker rules can apply. We confirm what applies when you start.
someone got hurt? make one call.
We file the report, get care moving and follow up until they’re back at work.

1. Report it
Tell us what happened. We file the first report with the carrier.
2. Care starts
Your employee sees a doctor. The policy pays the medical bills.

3. We stay on it
Lost wages and getting back to work. We follow up until it’s closed.
the best price, without the shopping.
Tell us about your business once. We compare the market and bring back your options, side by side.
Harbor Carpentry
your options
3 options, same coverage
Option A$24,800
Option B$26,900
Option C$29,300
coverage,
best price

switching takes one signature.
Keep your broker until the numbers say move. We do the paperwork.

1. Send your policy
Your current policy is enough. No forms.

2. We compare
Coverage, service and price, side by side with today’s options.

3. You choose
Stay or switch. If you switch, we handle the paperwork.
people who buy workers’ comp
also buy.
Put them on one program and we shop them together at every renewal.


good to know.
Straight answers about workers’ comp.
Do I need workers’ comp if I only have one employee?
Are business owners covered by workers’ comp?
What happens at the workers’ comp audit?
Do 1099 contractors count for workers’ comp?
Does workers’ comp cover an employee hurt in another state?
Insurance words, in plain English: waiver of subrogation · certificate of insurance · notice of cancellation · experience modification rate · class code · premium audit · exposure basis · uninsured subcontractor charge

see what your
program is missing.
Most have gaps. Find yours with a policy review.
get startedor call 802-GOT-RIZA