
Business owner’s policy
the basics, bundled.
Liability, property and lost income in one policy, usually for less than buying them apart. We shop the market and stay with you through the claim.
get startedMARKETS WE PLACE THROUGH



one policy, most bad days.
Trips, leaks, fires and closing for repairs. Tap around the shop to see what’s covered, and what isn’t.
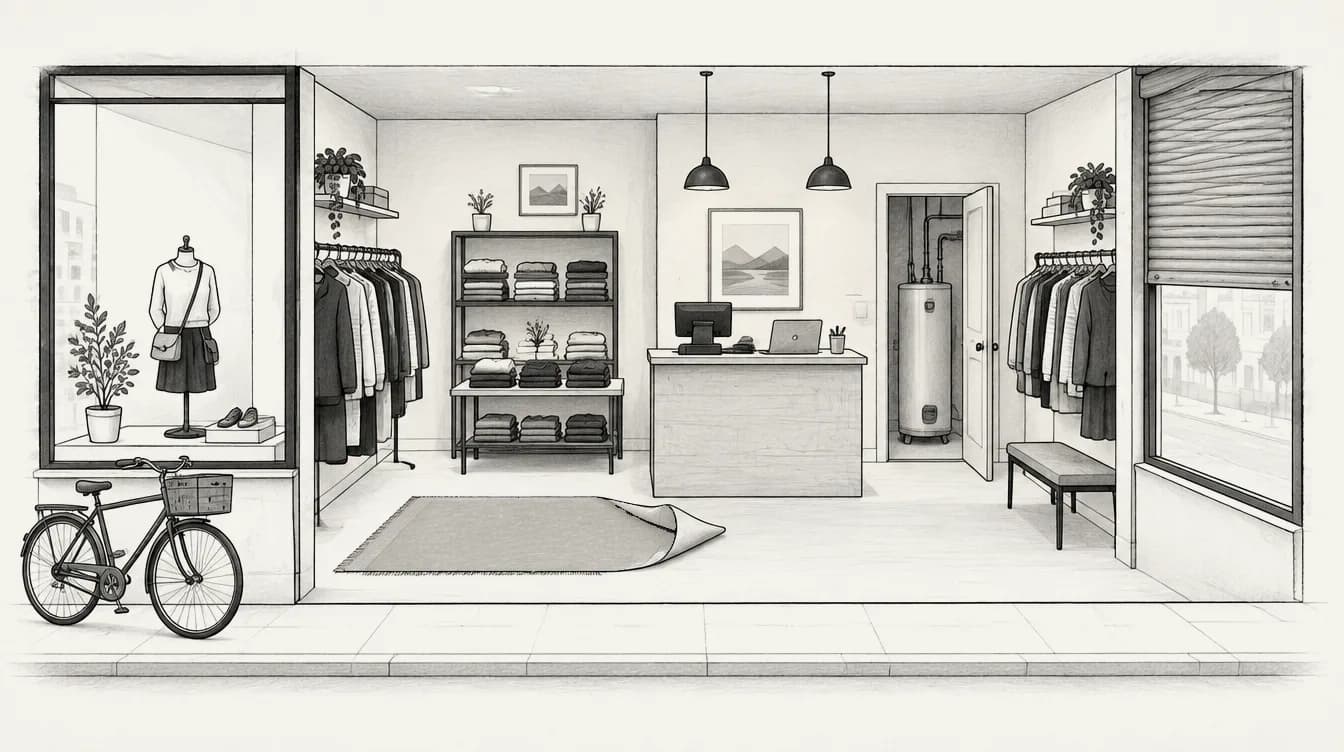
covered
A customer trips on the rug
Their medical bills and your legal costs.
covered
The water heater floods the back
Sudden leaks, plus the stock they ruin.
covered
A fire ruins your stock
Replaced, so you can reopen.
usually covered
You close for repairs
Lost income while you’re shut for repairs.
covered
A customer trips on the rug
Their medical bills and your legal costs.
Examples. Your policy sets the details.
bad day? make one call.
We build the claim, send it in and follow up until it’s closed. You get back to work.

1. Call us
You talk to your advisor, not a call center.

2. We build the claim
Photos, bills and the policy, put together and sent in.

3. We push it through
We follow up with the carrier until it’s settled.
the best price, without the shopping.
Tell us about your business once. We compare the market and bring back your options, side by side.
Harbor Boutique
your options
3 options, same coverage
Option A$1,450
Option B$1,620
Option C$1,890
coverage,
best price

switching takes one signature.
Keep your broker until the numbers say move. We do the paperwork.

1. Send your policy
Your current policy is enough. No forms.

2. We compare
Coverage, service and price, side by side with today’s options.

3. You choose
Stay or switch. If you switch, we handle the paperwork.
people who buy a business owner’s policy
also buy.
Put them on one program and we shop them together at every renewal.


good to know.
Straight answers about business owner’s policies.
What does a business owner’s policy cover?
Who qualifies for a business owner’s policy?
Is a BOP cheaper than buying policies separately?
Does a BOP include workers’ comp?
Can I add coverage to a business owner’s policy?
Insurance words, in plain English: business income and extra expense · coinsurance · replacement cost vs actual cash value · hired and non-owned auto

see what your
program is missing.
Most have gaps. Find yours with a policy review.
get startedor call 802-GOT-RIZA