
Business income insurance
close for
repairs, not
for good.
If a fire or storm shuts you down, business income replaces the money you’d have made and keeps payroll and rent paid while you rebuild.
get startedMARKETS WE PLACE THROUGH



the doors close. the income doesn’t.
Lost sales, payroll and temporary moves. Tap around the street to see what’s covered, and what isn’t.
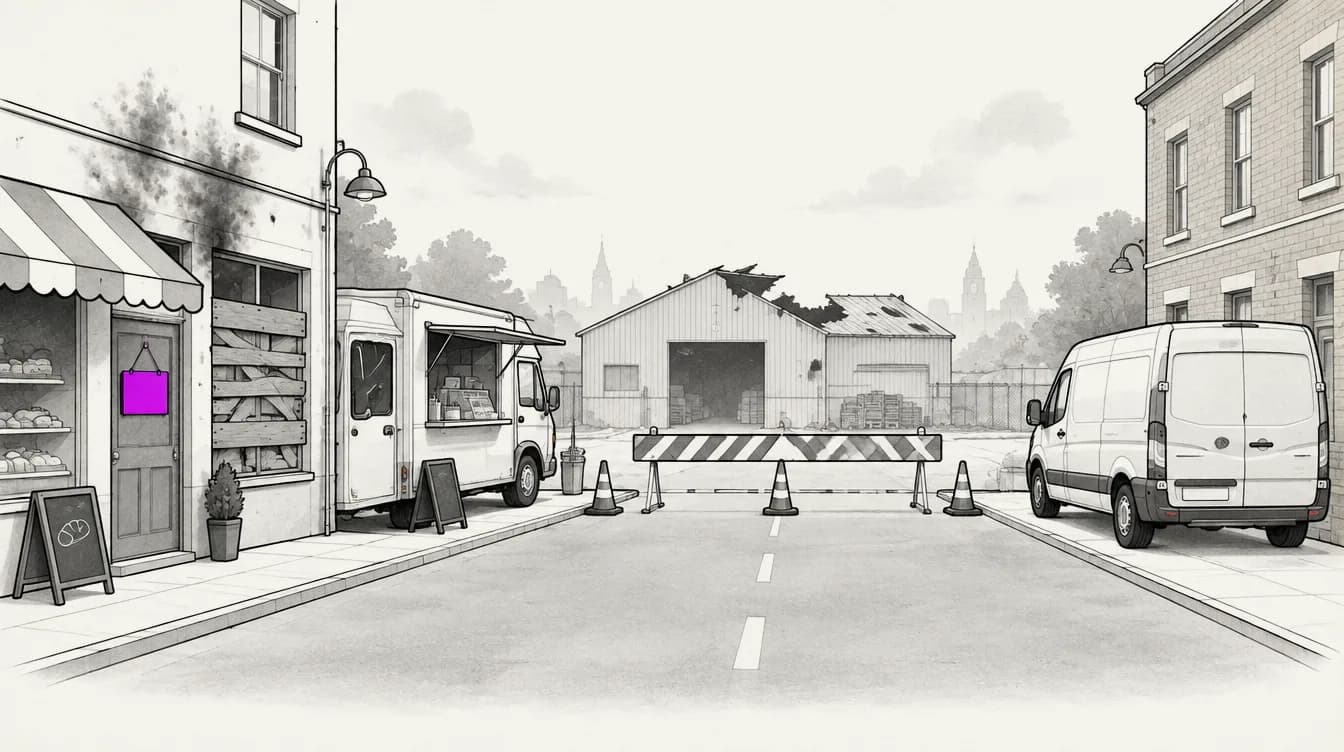
covered
You close after a fire
The income you would have made.
covered
Payroll keeps running
Your team gets paid while you’re shut.
usually covered
You reopen somewhere temporary
Extra costs to keep serving customers.
usually covered
The city blocks your street
When nearby damage closes your street.
not covered
Your supplier shuts down
That needs an add-on
covered
You close after a fire
The income you would have made.
not covered
Your supplier shuts down
That needs an add-on.
Examples. Your policy sets the details.
closed for repairs?
still paid.
Pick a point in the rebuild to see what adds up.
Month 1
Rent, payroll and
your lost profit.
Business income keeps paying until you reopen, up to your limit.
Rent $8,000, Payroll $42,000, Lost profit $15,000. Total $65,000 paid so far to Harbor Kitchen.
closed?
make one call.
We build the numbers the carrier needs, then follow the claim until you’re back open.

1. Call us after the loss
Tell us what happened and when you had to close.

2. We build the numbers
Your past sales, payroll and bills, packaged for the carrier.

3. We push it through
Payments while you rebuild, followed to the end.
the best price, without the shopping.
Tell us about your business once. We compare the market and bring back your options, side by side.
Harbor Kitchen
your options
3 options, same coverage
Option A$1,100
Option B$1,300
Option C$1,550
coverage,
best price

switching takes one signature.
Keep your broker until the numbers say move. We do the paperwork.

1. Send your policy
Your current policy is enough. No forms.

2. We compare
Coverage, service and price, side by side with today’s options.

3. You choose
Stay or switch. If you switch, we handle the paperwork.
people who buy business income
also buy.
Put them on one program and we shop them together at every renewal.


good to know.
Straight answers about business income insurance.
What does business income insurance cover?
Is business income the same as business interruption insurance?
Does business income insurance cover payroll?
How long does business income coverage last?
Do I need property damage for business income to pay?
Insurance words, in plain English: business income and extra expense

see what your
program is missing.
Most have gaps. Find yours with a policy review.
get startedor call 802-GOT-RIZA