



General contractor insurance. Built around your next project.

You bring the project together. We help bring the insurance together, from the owner’s requirements to the people, equipment and finished work you need to protect.

Prefer to talk? Call +1 802-GOT-RIZA · Sun to Sat, 8am to 8pm ET

  • Compare available coverage and price
  • Check requirements before the job starts
  • One broker as your business grows
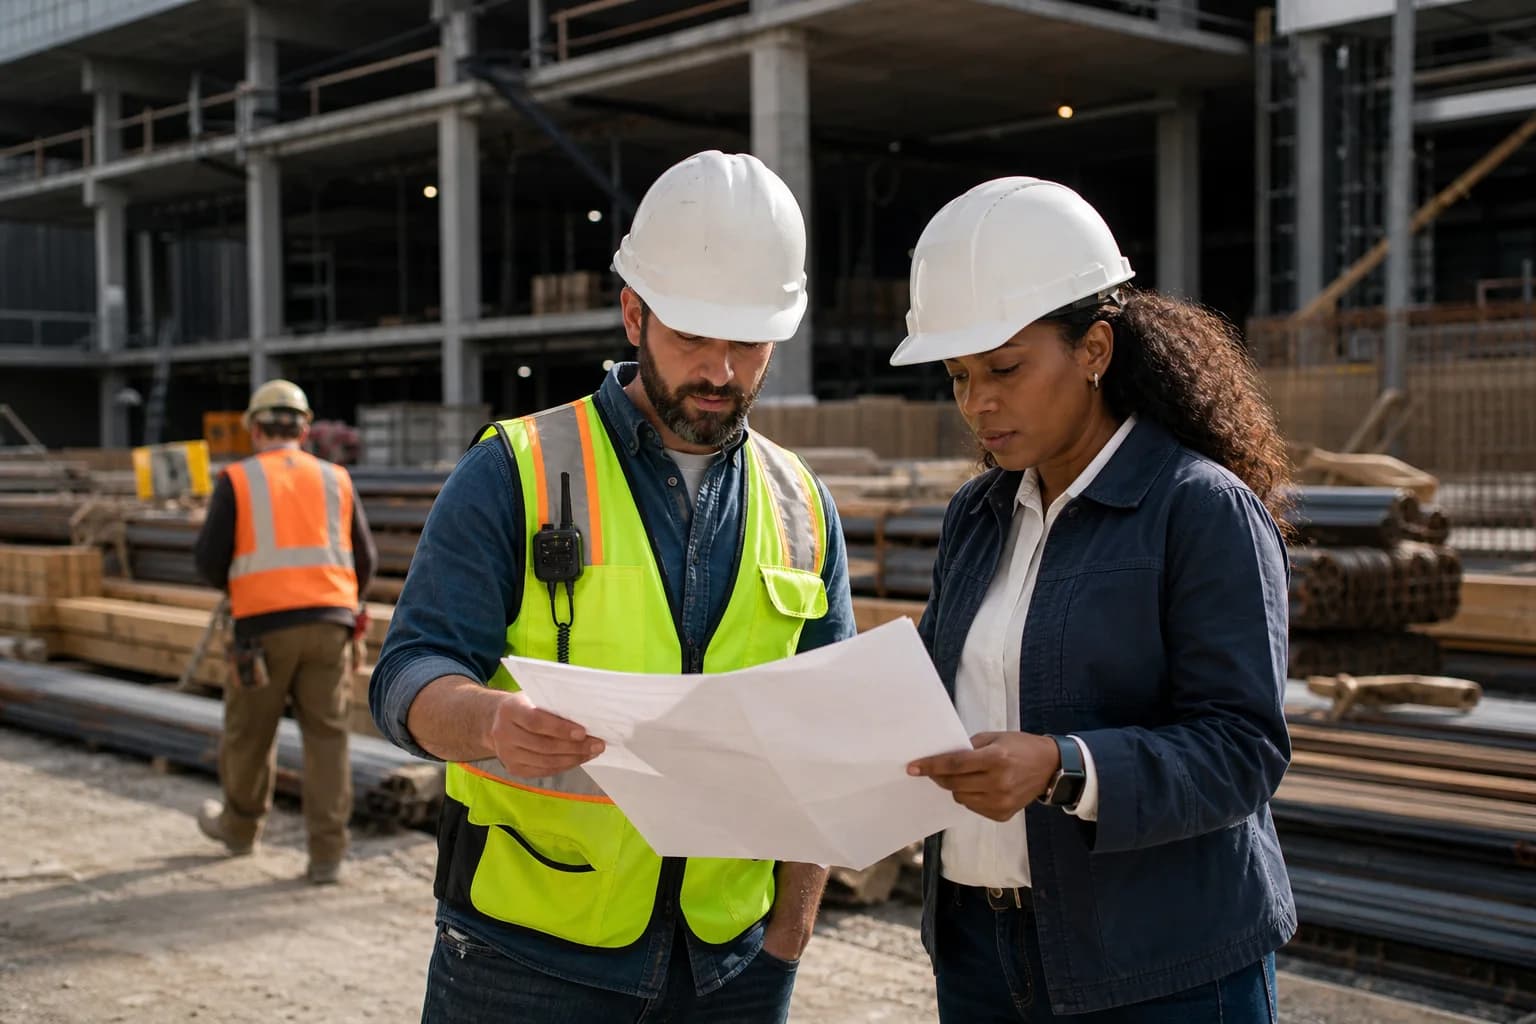
General contractors reviewing a building project on site

Markets we place through.

Progressive Commercial
Chubb
Travelers
Nationwide
AmTrust
CNA
biBerk
ERGO NEXT
THREE

You’re responsible for more than the schedule.

The property. The crew. The unfinished build. Different risks need different protection. We help you connect the dots before the job starts.

Your work · General liability

A renovation damages more than the room you’re working in.

  • Damage to the owner’s existing property can become a claim against your business, even when a subcontractor did the work.
  • We help check your general liability terms for resulting damage, subcontracted work and exclusions. Fixing defective work is a different question.
  1. General contractor

    My sub damaged the owner’s floor. Is that on me?

  2. Riza

    Your business could be named too. Let’s check both policies.

  3. General contractor

    Even if I have their certificate?

  4. Riza

    Yes. Protection comes from the policy and endorsements, not the certificate.

Your people · Workers’ compensation

Look after the people behind the project.

  • A work injury can mean medical bills and time away from the job. Workers’ comp helps with covered treatment and wage benefits under state rules.
  • Before you add to the crew, we help sort out employee, owner and subcontractor questions so you know who needs protection.
  1. General contractor

    We’re adding two carpenters for this project.

  2. Riza

    Let’s review their duties, payroll and where they’ll work.

  3. General contractor

    What if I pay them on a 1099?

  4. Riza

    The working relationship and state rules matter, not just the tax form.

The project · Builders risk

Protect the build before you hand over the keys.

  • A fire or theft during construction can put the building and materials at risk. Builders risk addresses covered project property, not the same risks as general liability.
  • We help check who arranges the policy, whose interests it covers and how protection lines up with the project dates.
  1. General contractor

    The owner is buying builders risk. Are we set?

  2. Riza

    Let’s confirm whose interests it covers and when it starts.

  3. General contractor

    And materials stored off site?

  4. Riza

    That needs checking too, along with materials in transit.

One business. More than one kind of protection.

Start with the jobs you run and who does the work. We’ll help you build a program around both.

Your projects

Liability
The job and what followsOperations, contracts and subcontractors
General liability

Help protect your business against covered injuries to others and property damage, including certain claims from completed work.

Explore general liability

Your people

State rules
The crew behind the buildPayroll, duties and injury protection
Workers’ compensation

Medical care and wage benefits for covered employee injuries. Check employee, owner and subcontractor treatment before a job starts.

Explore workers’ comp

Your vehicles

On the road
Trucks, vans and driversLiability and vehicle damage are separate choices
Commercial auto

Help protect the driving between projects. Review your trucks, drivers and use of vehicles you don’t own.

Explore commercial auto

Your equipment

On the job
Owned or rentedValues, storage and transport matter
Tools & equipment

Check protection for gear at the shop, in transit and on site, including rented equipment and theft conditions.

Explore tools & equipment

Placing the policy is half the job.

We stay for the other half. Four things that happen when a broker is on the account.

Win the project.
Know what the contract asks.

  • Insurance requirements compared with your policy
  • Additional insured and completed-work terms explained
  • Open coverage questions flagged before you commit
  • Certificates issued from the policy as written
New contractTenant improvement · example
Received 9:41 AM
Insurance requirementOwner’s insurance exhibit
Before mobilizationReviewing insurance language
Requirement review3 of 3 matched
Liability limitsCompare with the contract
Matched
Additional insuredCheck the endorsement
Matched
Completed workReview required duration
Matched
ActivityToday
9:41Contract received and read
9:43Requirements checked against the policy
9:47Certificate drafted for Tenant improvement · example
PDF
Certificate packageConfirm coverage before issuing
Send COI

Win the project.
Know what the contract asks.

  • Insurance requirements compared with your policy
  • Additional insured and completed-work terms explained
  • Open coverage questions flagged before you commit
  • Certificates issued from the policy as written
New contractTenant improvement · example
Received 9:41 AM
Insurance requirementOwner’s insurance exhibit
Before mobilizationReviewing insurance language
Requirement review3 of 3 matched
Liability limitsCompare with the contract
Matched
Additional insuredCheck the endorsement
Matched
Completed workReview required duration
Matched
ActivityToday
9:41Contract received and read
9:43Requirements checked against the policy
9:47Certificate drafted for Tenant improvement · example
PDF
Certificate packageConfirm coverage before issuing
Send COI

A bigger job.
A fresh look at your coverage.

  • New employees and subcontracted operations reviewed
  • Vehicle and equipment changes sent to the carrier
  • New project types considered before work begins
  • Requested changes confirmed before you rely on them
Coverage reviewGrowing business · example
Updated
ProjectsRemodelsNew construction
WorkforceOwn crewCrew + subcontractors
Operations endorsementIssued
Same account, same brokerIllustrative confirmed update
ActivityToday
9:52Projects updated, Remodels to New construction
10:05Workforce updated, Own crew to Crew + subcontractors
11:20Operations endorsement, carrier confirmed
COI
CertificateIllustrative confirmed update
Sent

When something happens,
you have someone to call.

  • Help reporting the incident to the carrier
  • Project records and photos organized
  • Support with questions about the next step
  • The carrier determines coverage and claim payments
ClaimRenovation incident · example
Reported
IssueExisting property damaged
RecordsContract and site photos
Next stepCarrier review
StatusIllustrative example
Status checked by your brokerPolicy terms and facts determine coverage
ActivityToday
9:14Reported once, to your broker
9:31Sent to the carrier with the file attached
10:05Adjuster assigned, direct line on file
CL
Next stepAdjuster call, your broker on the line
On calendar

Your next year
deserves a fresh comparison.

  • Upcoming projects and business changes considered
  • Available coverage and prices compared
  • Exclusions and payment terms explained
  • You decide whether to stay or switch
CompareCurrent vs option
Side by side
ProjectsThis year’s workNext year’s plans
SubcontractorsCurrent mixUpdated operations
TermsCurrent policyAvailable alternatives
Option BSelected
Stay or switch, your callIllustrative comparison, not a quote
ActivityToday
MonCurrent policy received, terms read
WedOptions placed side by side, coverage first
FriIllustrative comparison, not a quote, packet drafted
PDF
Renewal packetReady to sign
Open

A price for your business. Not someone else’s.

A one-person remodeler and a GC running several builds need different quotes. Here is what helps us find the right fit.

01
What you build.

Residential, commercial, structural work and occupied renovations can raise different coverage questions. Include what you subcontract as well as what you perform.

02
Who does the work.

Payroll, receipts and subcontractor costs may affect rating and audits. Keep records of duties, payments and subcontractor insurance.

03
The size and location of your projects.

Your largest jobs, states and construction methods help carriers assess the work. A familiar project size can still carry a new kind of risk.

04
The protection you choose.

Limits, deductibles, exclusions and required endorsements change the comparison. Check the full-term cost, not only the monthly payment.

05
Your claims and what has changed.

Bring accurate loss information and documented improvements. We help explain the business; the carrier decides the terms it can offer.

Your projects shape your insurance.

Tell us where you work, what you build and which parts you take on yourself.

Occupied spaces

Protect the work and what is already there.

Your next project

  1. Homes or commercial spaces?
  2. Structural changes or finish work?
  3. Will people remain in the building?

What we check

  • Existing propertyCompare damage-to-property exclusions with the actual work.
  • SubcontractorsCheck the trades you hire and the policy’s conditions.
Get a quote

Your answers come with you. We confirm what applies when you start.

From ground to handover

Plan for the build and the years after it.

Your next project

  1. Who buys the project property policy?
  2. What work will your own crew perform?
  3. What completed-work terms does the owner request?

What we check

  • Project propertyBuilders risk and general liability protect different interests.
  • Finished workReview exclusions, policy periods and required endorsements.
Get a quote

Your answers come with you. We confirm what applies when you start.

Owner requirements

Know the insurance ask before you price the job.

Your next project

  1. What limits does the owner require?
  2. Is there a wrap-up insurance program?
  3. Are you taking on design responsibility?

What we check

  • Contract requirementsRead the requested endorsements, not only the limit.
  • Separate coverageAsk about design, pollution and wrap-up participation rather than assuming GL covers them.
Get a quote

Your answers come with you. We confirm what applies when you start.

A better renewal starts with the policy you already have.

Already insured? Send it once. We compare it with today’s options.

Send

PDFCurrent policy.pdfGeneral liability · Auto · Workers’ comp
Policy received
01

Send your current policy. No blank forms.

Compare

Liability limit$1M$2M
Deductible$2,500$1,000
Annual premium$6,840$6,420
02

See coverage, service, and price side by side.

Choose

Current policy$6,840 / year
Option A$6,420 / yearSelected
03

Stay or switch. We organize the next steps.

Compare my current policy

Built for the places you work.

State rules, local permits and owner contracts are separate checks. Start with your state.

Licensed in Arizona

Change it if that is not where the work is.

Arizona general contractor insuranceCoverage, local requirements and the next project

General contractor insurance by state

Plain answers before the next job.

What general contractors ask before choosing insurance.

What insurance does a general contractor need?

Start with general liability for covered injuries to others and property damage, workers’ comp for employee injuries, and commercial auto for business driving. Tools and equipment, builders risk, umbrella, professional liability or pollution coverage may also matter. The right combination depends on your projects, workforce, contracts and state rules. Riza helps you compare the actual work with available policies before you decide.

Is general contractor insurance the same as general liability?

No. General contractor insurance describes a collection of policies for the business. General liability is one part of it. It does not replace workers’ comp, auto insurance or protection for the building under construction. Start with what could interrupt the business, then check which policies address those risks and what the owner’s contract requires.

Do I need insurance if all my work is subcontracted?

Using subcontractors does not remove your own potential liability. Your business can still be named in a claim involving their work. Check your policy’s subcontractor conditions, written contracts and the insurance each subcontractor carries. Workers’ comp obligations can also depend on state law and the working relationship. A certificate alone does not settle those questions.

Does general liability cover construction defects?

It may cover certain resulting bodily injury or property damage, but it is not a warranty that pays to correct every defective job. Your-work exclusions, subcontractor wording, residential or other operation restrictions, and the timing of damage can change the answer. Review the actual policy and facts rather than treating the phrase construction defect as one covered category.

What is the difference between builders risk and general liability?

Builders risk generally protects covered project property during construction, subject to its terms. General liability addresses covered liability to others for injury or property damage. Neither automatically replaces the other. Check who is arranging the builders risk policy, which interests and materials it covers, and when coverage ends, especially during renovation, partial occupancy or delayed completion.

Can Riza compare my current insurance?

Yes. Bring your current policies and tell us about upcoming projects, subcontractor use and changes in the business. We help compare available options, explain differences in coverage and price, and coordinate requested changes. You decide whether to stay or switch. Confirm replacement coverage is effective before cancelling an existing policy.

How do I get a general contractor insurance quote?

Start with the quote request and a conversation about your work. Your locations, project types, revenue, payroll, subcontractor costs, vehicles and loss history help establish what carriers need. If you have a current policy or an owner’s insurance exhibit, bring it. The quote is broker-led; submitting the request does not bind coverage or guarantee an instant price.

You build what comes next. Let’s help protect it.

Tell us about your projects, or bring the policy you already have.

Prefer to talk? Call +1 802-GOT-RIZA · Sun to Sat, 8am to 8pm ET