
Commercial food equipment insurance
keep the
kitchens
cooking.
Liability, comp, trucks and tools for food equipment techs serving restaurants, schools and hospitals, with the vendor certificates those kitchens ask for.
get startedMARKETS WE PLACE THROUGH



a bad day in
the kitchen, covered.
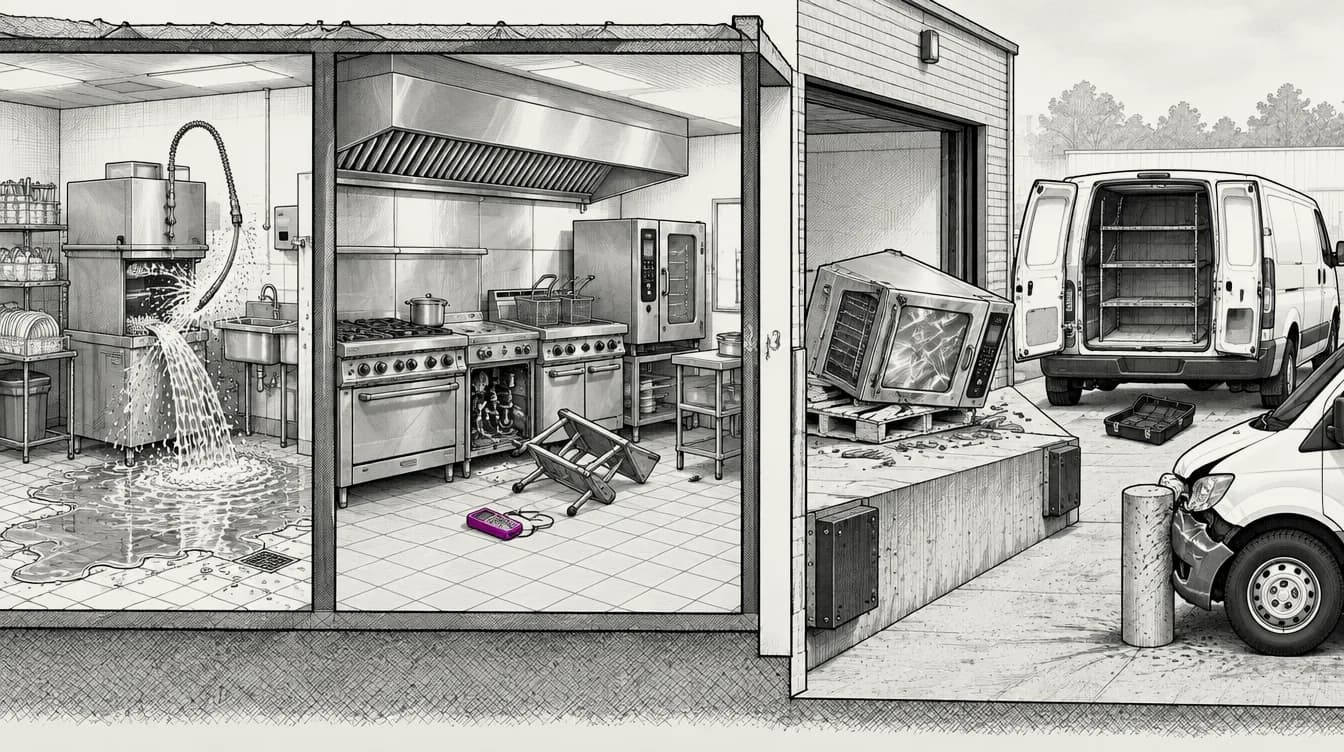
A flooded dish room, a dropped oven, a fender bender. Tap around to see which policy steps in.
general liability
A dish machine hose lets go
Water damage to the customer’s kitchen.
workers’ comp
A tech is hurt working the cooking line
Medical bills and lost wages.
installation
A new oven falls off the pallet
Equipment you’re installing, before the customer takes it over.
tools and equipment
The toolbox gets stolen from the van
Tools and gear, on the job or on the road.
commercial auto
The van noses into a bollard
Damage you cause on the road.
general liability
A dish machine hose lets go
Water damage to the customer’s kitchen.
Examples. Your policy sets the details.
the work changes
what we check.
Cooking lines, dish rooms and new kitchens carry different risks. Pick yours.
Cooking equipment
Hot side, open for business.
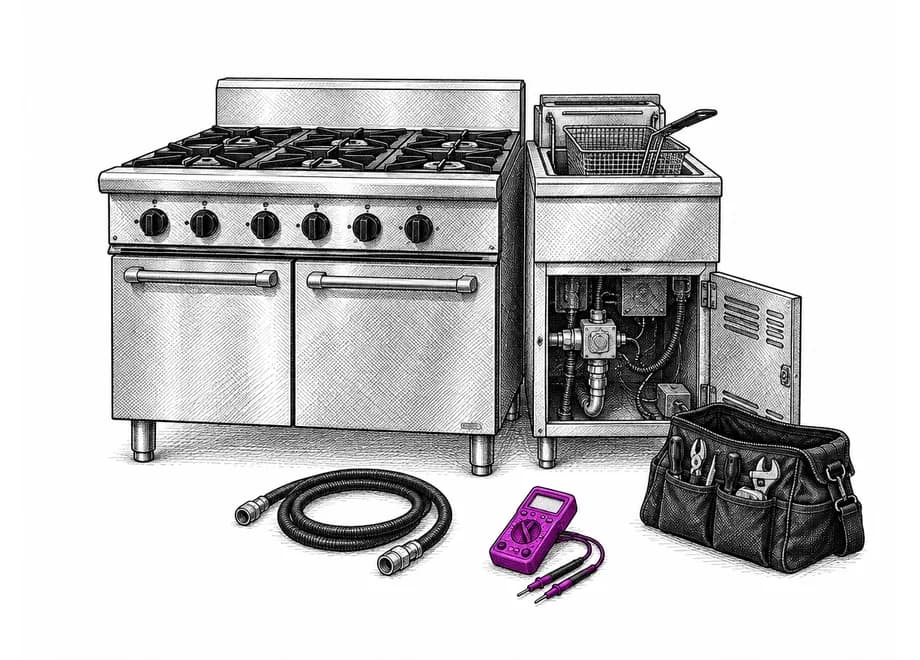
We check how gas, electrical and ventilation work behind the ovens, fryers and ranges is described to the carrier, in kitchens that stay open while you work.
we check first: Gas and electrical work. Illustrated six‑burner range beside a fryer with its lower panel open on the gas valve, a coiled gas hose, a tool bag and a purple multimeter
food equipment service businesses
usually carry.
Put them on one program and we shop them together at every renewal.


flooded kitchen?
make one call.
We file it, get an adjuster on it and follow up until it’s closed.

1. Call us from the job
Tell us what happened and send a few photos.

2. We file it
Photos, notes and the customer’s details go to the carrier.

3. We push it through
Repairs, the customer’s claim and your payout, followed to the end.
the best price, without the shopping.
Tell us about your business once. We compare the market and bring back your options, side by side.
Lineside Kitchen Service
your options
3 options, same coverage
Option A$16,800
Option B$18,300
Option C$19,900
coverage,
best price

switching takes one signature.
Keep your broker until the numbers say move. We do the paperwork.

1. Send your policy
Your current policy is enough. No forms.

2. We compare
Coverage, service and price, side by side with today’s options.

3. You choose
Stay or switch. If you switch, we handle the paperwork.
guides
kitchen techs ask for.
The coverage behind a kitchen call.
growing by
acquisition?
Buying another food equipment service shop, backed by private equity or getting ready to sell? We cover the deal and the company you’re building.
- Buying a shopWhat the business you’re buying carries, what it’s missing and what it will cost to fix, before you close.
- Backed by private equityOne program across every location you add, set up to grow with every add-on.
- Building by acquisitionCoverage for the holding company and each add-on, placed and renewed together.
good to know.
Straight answers about commercial food equipment insurance.
What insurance does a commercial food equipment business need?
Does general liability cover water damage from a dish machine repair?
What affects the price of commercial food equipment insurance?
Why should cooking equipment and refrigeration work be separated?
Is equipment I’m installing covered before the customer takes it over?
Insurance words, in plain English: certificate of insurance · additional insured · waiver of subrogation · class code · premium audit · uninsured subcontractor charge

see what your
program is missing.
Most have gaps. Find yours with a policy review.
get startedor call 802-GOT-RIZA